Last updated: November 18, 2026
Pet insurance works by reimbursing you for eligible vet bills after you pay the clinic. You pay a monthly premium, cover a deductible, and the insurer repays a percentage of the rest, up to an annual limit. Unlike human health insurance in the U.S., you can usually visit any licensed vet. Here’s how each piece works, with a worked example.
The short version
| Term | What it means | Common options |
|---|---|---|
| Premium | What you pay each month for the policy | Depends on species, breed, age, location and coverage |
| Deductible | What you pay before the insurer starts paying | $100–$1,000, usually per year |
| Reimbursement rate | The share of the eligible bill the insurer repays | 70%, 80% or 90% |
| Annual limit | The most the policy pays in a policy year | A few thousand dollars to unlimited |
| Waiting period | Time after you enroll before coverage starts | Often days for accidents, longer for illnesses |
How a claim works, step by step
- Your pet sees any licensed vet, and you pay the bill as usual.
- You send the invoice and medical records to your insurer, usually through an app.
- The insurer checks that the treatment is covered and not related to a pre-existing condition.
- It subtracts your deductible, applies your reimbursement rate and sends you the money.
Some insurers can pay the vet directly, but most reimburse you, so you still need a way to cover the bill up front.
A worked example
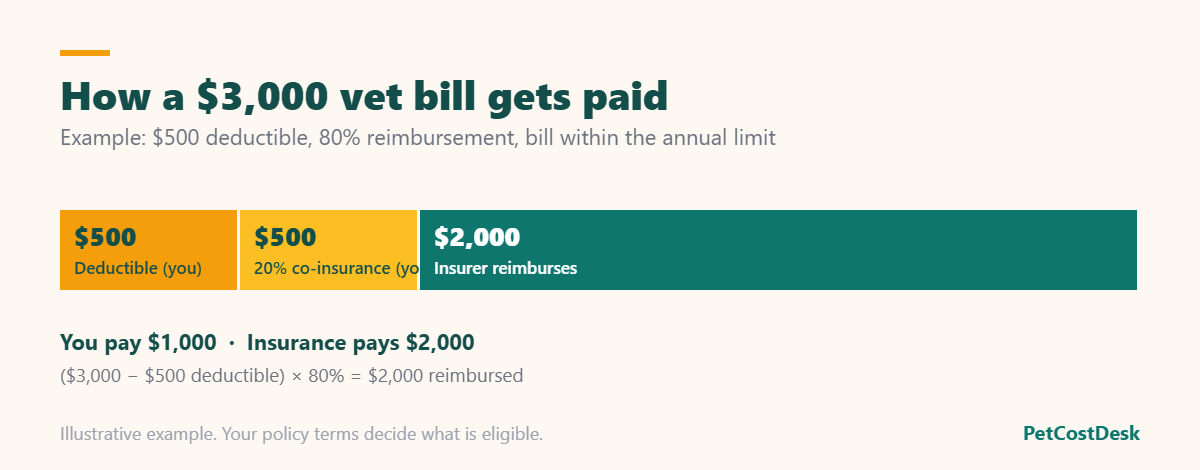
Say your dog needs treatment that costs $3,000, and your policy has a $500 annual deductible, 80% reimbursement and a $10,000 annual limit. You pay the first $500. The insurer then pays 80% of the remaining $2,500, which is $2,000. Your total out of pocket is $1,000. Later claims in the same policy year skip the deductible, since you’ve already met it.
What’s usually covered and what isn’t
Accident and illness plans typically cover injuries, illnesses, emergency care, surgery, hospitalization, diagnostics and prescription drugs. Accident-only plans cover injuries but not illnesses. Compare them in accident-only vs. accident and illness plans.
Most policies exclude pre-existing conditions, which means problems your pet showed signs of, or was treated for, before coverage started or during the waiting period. Routine care such as checkups and vaccines is usually covered only by an optional wellness add-on, which isn’t insurance.
Rules that protect you
The National Association of Insurance Commissioners adopted a Pet Insurance Model Act in 2022, which states can adopt. It requires insurers to clearly disclose waiting periods, limits and pre-existing condition rules, keeps wellness programs separate from insurance, and puts the burden on the insurer to show that a pre-existing condition exclusion applies. Check your state’s rules and your policy documents.
What it costs
Accident and illness plans averaged about $836 a year for dogs and $435 for cats in 2025. See how much pet insurance costs for what changes the price, and is pet insurance worth it? to decide whether you need it.
Key takeaways
- Pet insurance usually reimburses you after you pay the vet, and you can use any licensed vet.
- Your deductible, reimbursement rate and annual limit decide how much you get back.
- Pre-existing conditions are excluded, and routine care needs a separate wellness add-on.
- Read waiting periods and exclusions before you buy.